Do blockchain systems reduce the costs of know your customer compliance?
KYC requirements cost the financial sector billions annually. Can blockchain systems reduce the costs? We talked with Michael F. Spitz, CEO of Commerzbank innovation subsidiary Main Incubator.
- 25 billion dollars is what experts estimate to be the annual costs of meeting know your customer obligations in the financial sector.
- In the search for more efficient and less expensive solutions, banks consider blockchain applications, among other things.
- Michael F. Spitz, CEO of Commerzbank innovation subsidiary Main Incubator, shares his views in an interview with EOS.
What then is the advantage of blockchain in the field of know your customer (KYC), where there are rigorous requirements, for example, imposed by the Money Laundering Act?
Take corporate clients: they usually have relationships with multiple banks. And they have to give each of these banks the same information, which is inconvenient. That is where blockchain offers the possibility to provide the information to a bank once and allow the next bank to access it.
But the second bank must trust in the fact that the first bank checked the customer’s data.
Exactly. In order for this trust to arise, we need an independent instance. Take the commercial registers or land registers: they are classic directories monitored by authorities and hence trustworthy, but they still only contain very specific information. For KYC in the financial sector, you need a lot of information, for example, whether there are politically exposed people in the company or who the beneficial owners are.
More data, more responsibility: That’s what know your customer regulations mean.
“Know your customer” is the term used for prescribed identity checks on new customers. The extent to which financial companies and other sectors must verify and document the identities of their customers is a consequence of the anti-terrorism legislation of the early 2000s. The fourth Anti-Money Laundering Directive (EU 2015/849) is currently valid in the EU. Added to this is the GDPR, which imposes stricter requirements on companies for handling sensitive data.
Why do I need a blockchain for such a directory? Why isn’t it enough to have a completely normal database, which authorized parties can access?
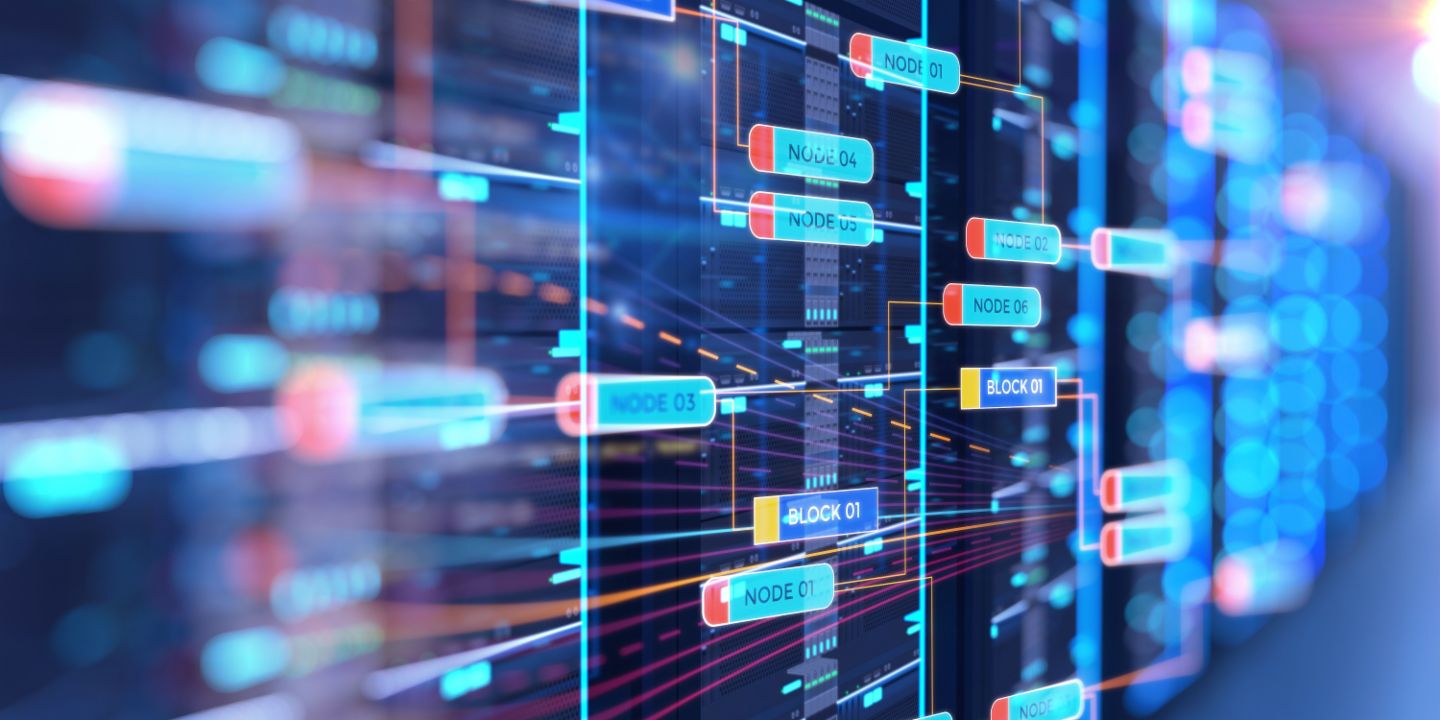
The advantage of a blockchain solution is that the information comes from multiple network nodes and cannot be changed. One bank verifies the address of the customer, and another bank verifies the bank account information of a customer, and in total, I always have a distributed verified data record. I can always trace it back: Where did the information come from? Is it still valid? And the customer can always see who accessed this information and decide whether that is wanted or not.
So for me as a customer, that means the database is not a black box and I can decide what will happen with my data?
And that is a very important advantage: it is about ethics and transparency. We have to give the people who own the information the power to control this information too instead of just entering it into a black box. This is called the “self-sovereign identity”: if I have my information in this blockchain-based system, I can, for example, inform three banks of who my authorized signatories are. I might give my address to 15 parties and my bank account information to seven banks for euro transactions, but only to two banks for dollar transactions.
Good, but why should the banks trust the information coming from the blockchain system?
Because each piece of information was verified by two independent third parties. This is a change from a centralized to a decentralized instance. A lot of research is being done on so-called permission systems: they ensure that participants only feed in and retrieve information in such a way that consensus and trust ensue. With popular blockchain applications such as Bitcoin, the trust comes from the fact that hundreds of anonymous network nodes verify a transaction. With our topics, KYC and finance, you will have much fewer network nodes because there is a manageable number of market participants and institutions, who usually know each other.
When you say “institutions,” do you also mean “authorities”?
Yes. When I give a regulator or stakeholders a node in this private blockchain, all my reporting obligations are met without manual processes, without paper, and that of course represents huge savings.
But if the state is only one of several participants, who then is running this blockchain-based trusted platform? Can it be a bank?
If it succeeds in building, apart from its existing brand, the trustworthiness on the technology side, yes. We as Main Incubator have also already acted as platform operators for blockchain-based securities transactions. You are up against players such as Microsoft or IBM and have to show that you are more suitable – for reasons of security, speed, and costs. This is a very typical market environment that you have to work.
Michael F. Spitz is CEO of Main Incubator GmbH, an outsourced R&D unit of Commerzbank, with offices in London and Frankfurt. Main Incubator cooperates with universities and the fintech community, acts as an early stage investor, and runs a prototyping lab for financial innovations.
Are you a financial service provider with questions about EOS? Contact us.
EOS Deutschland GmbH I B2B unit
EOS KSI Kundenservice
Telefoon: +49 7066 9143 9999
Photo Credits: Juhari Muhade / Getty Images, Westend61 / Getty Images, Torsten Silz / FernUni Hagen
Ontdek meer van EOS