- People facing payment difficulties are more open to AI in bank communications than those who are not
- Openness to AI does not mean replacing personal contact, however
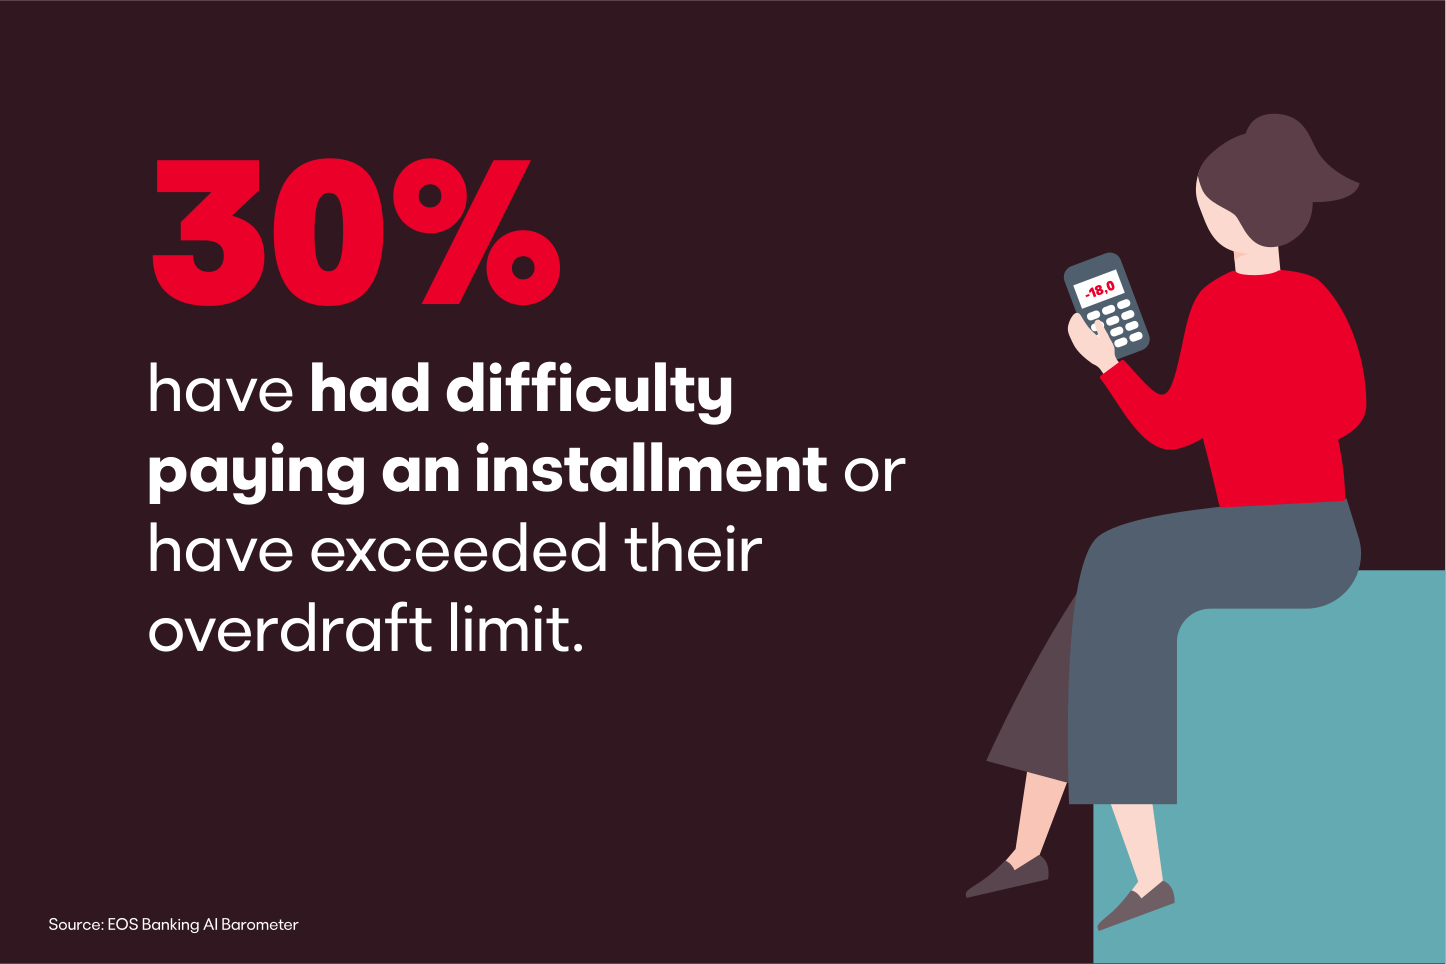
- 30 percent of consumers have experienced payment difficulties with their bank, and one in four has already been in touch with a debt collection agency
People who have experienced payment difficulties are significantly more open to AI-supported communication from banks than those who have not. At the same time, most people still do not want to give up personal contact with a human expert. This is shown by the EOS Banking AI Barometer, which surveyed consumers across eleven European countries on their attitudes toward AI in banking communication.
A key finding of the study: Experience with debt is by no means an exception. 30 percent of respondents stated that they had previously struggled to make an installment payment or had overdrawn their credit line. In addition, one in four had already been in contact with a debt collection company. This clearly shows that over-indebtedness and financial bottlenecks are challenges that many people face in everyday life.
How do people facing payment difficulties view the use of AI in banking?
Digital support tools are rated especially positively when it comes to sensitive topics like debt. This is one of the intriguing insights from the EOS Banking AI Barometer. People who have experienced payment difficulties with their bank often welcome proactive assistance: across all age groups, they view AI support offers more positively than people without comparable experience.
What kind of AI services do people facing payment difficulties want from their bank?
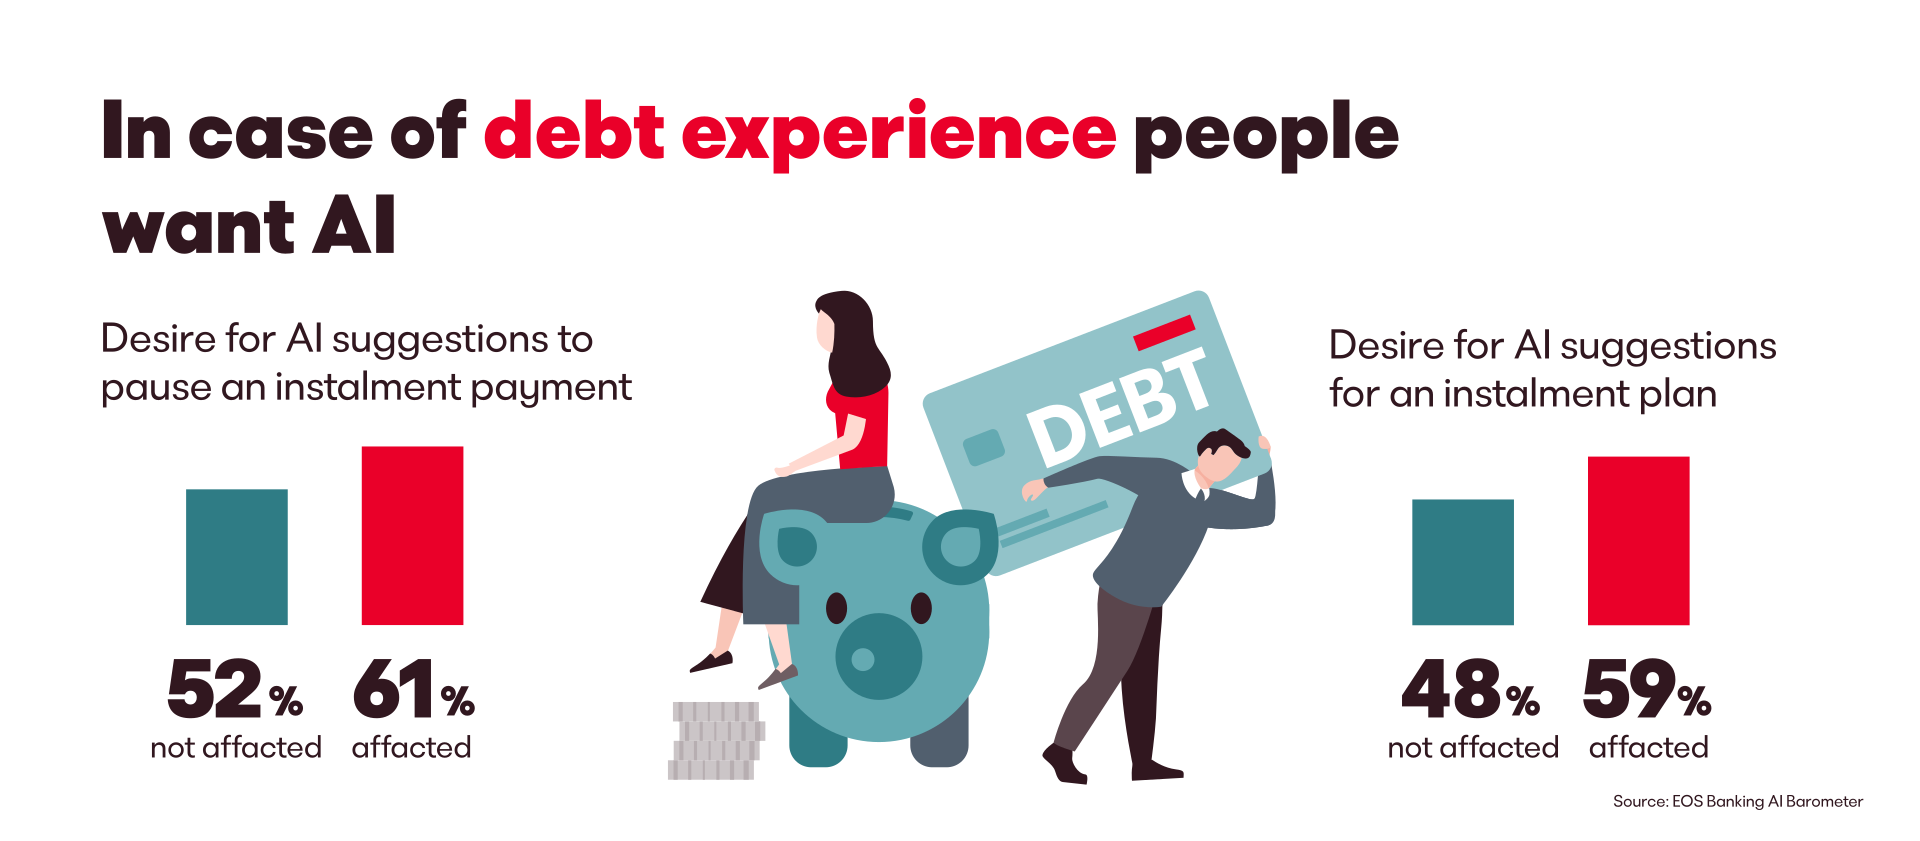
"61 percent of people facing payment difficulties would like AI to suggest suspending an installment – compared to only 52 percent of those without such experience,” explains Daniela Moaca, Senior Manager IT at EOS in Romania. “Low-threshold initial support and perceived anonymity could be reasons behind this preference for proactive AI.” Approval from people facing payment challenges is also higher when it comes to AI recommendations for an installment plan: 59 percent view these suggestions positively, compared to 48 percent of those without payment difficulties.
However, greater openness to AI does not mean that people want to have personal contact entirely replaced. 80 percent of respondents who have experienced payment bottlenecks still want a human expert involved when discussing this sensitive topic with their bank.
What do consumers value about interacting with AI?
Regardless of personal experience with payment bottlenecks, when facing sensitive topics such as financial difficulties or debt, 39 percent of consumers are already ready to accept AI as the first point of contact in their bank’s customer communication.
51 percent of bank customers view speed and 24/7 availability as key benefits of AI. We see the same trend in debt collection: at EOS, the use of online payment options and chatbots rose from 27.5 to 33 percent over the past year.
People who have experienced payment difficulties with their bank appreciate digital processes in particular. In fact, 13 percent of them could even imagine communicating exclusively with an AI. This may be because some individuals prefer the distance and anonymity of a technical solution when dealing with sensitive financial matters. Among those who have not faced payment difficulties so far, that figure is only 6 percent.
What can banks learn from the EOS study?
The findings suggest that digital banking services are valued at least as an accessible, low-barrier entry point to communication. However, personal advisory support remains both important and desired. From the banks’ perspective, this makes a compelling case for hybrid models that combine modern digital solutions with personal support.
For the EOS Banking AI Barometer study – How Europe really feels about AI in banking – 4,400 people in eleven European countries (Bulgaria, Croatia, France, Germany, Greece, Poland, Portugal, Romania, Slovenia, Spain, and Switzerland, 400 respondents per country) were surveyed about their attitudes toward artificial intelligence in bank communications. The data was collected in July 2026, and the target group consisted of bank customers aged 18 to 65. The study was conducted online and was representative of the population.
Would you like to learn more about the current EOS study? Feel free to reach out to us.
Carina Bonde
Corporate Communications & Marketing
Телефон: + 49 173 2979331
Explore more from EOS